Menu
Close

To provide the best experience, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to provide data such as browsing behaviour or unique IDs on this site. Not consenting or withdrawing consent may adversely affect certain features and functions.
Allow All
The Green Molecule is Atmen’s breakfast series, created to make room for the conversations that begin when new regulation meets the realities of the market.
A new rule rarely arrives with every answer attached. It sets a direction, but it also poses new questions. What is unique about this set of rules? How will they work in practice? How will they be interpreted?
For Spain’s RED III implementation, one question is particularly pressing: will the framework create the right incentives for supply and demand? And how might its impact differ for hydrogen producers, biomethane operators, fuel suppliers and those responsible for traceability?
The series brings these different perspectives into one room, creating space for an open exchange that moves beyond the legal text.
That openness is at the core of the format. For conversations to be genuinely valuable, people need to feel comfortable speaking openly. That's why The Green Molecule follows the golden Chatham House Rule, allowing insights to be shared without attribution to individuals or organizations. This article follows the same principle, bringing together key takeaways from Madrid while respecting the confidentiality of the discussions.
On 9 October, we brought the series to Madrid for the first time, co-hosted with Moeve, HEYGAZ Biomethane and Enagás, around one central question:
RED III implementation in Spain: what will change in practice over the coming year?
One of the clearest positives to emerge from the discussion was the long-term visibility provided by Royal Decree 611/2026.
The decree establishes annual targets through 2040, including road transport subtargets of 2.5% for RFNBOs and 5.5% for advanced biofuels and biogas by 2030. It also puts greenhouse gas (GHG) emissions reductions at the center of the broader transport framework, rather than relying solely on renewable fuel volumes.
That longer-term outlook comes with some flexibility. Under specific conditions and limits, certain renewable fuels used in other sectors or transport modes can contribute towards meeting relevant obligations.
Yet the regulatory framework is not complete. The draft SICCRE Ministerial Order, covering certificates, reporting and compensatory payments, was still under review at the time of the breakfast.
With Spain’s snap election scheduled for 29 November, participants also expressed concern that political uncertainty could delay the remaining steps needed to put the framework fully into practice.
While the decree provides a clearer long-term direction, the first years of implementation raise a more immediate question: will supply be ready in time?
Spain’s renewable fuel obligations begin increasing in 2027. Yet developing new production facilities and bringing certified fuels to market can take years, potentially leaving a gap between what the framework requires and what projects can realistically deliver.
For RFNBOs, one illustrative calculation shared during the breakfast put cumulative compensatory payments for 2027–2029 at around €1.3 billion, based on a limited set of projects that had reached final investment decision (FID) or were under construction. The figure was not presented as a forecast, but as an illustration of the potential scale of the timing mismatch.
Not everyone interpreted the challenge in the same way. Participants discussed whether Spain’s existing flexibility mechanisms could help bridge the gap, or whether additional measures might be needed.
Behind the numbers, a broader concern emerged: ensuring the early years of implementation support investment in new production capacity, so that rising obligations can be met through actual fuel supply rather than compensatory payments.
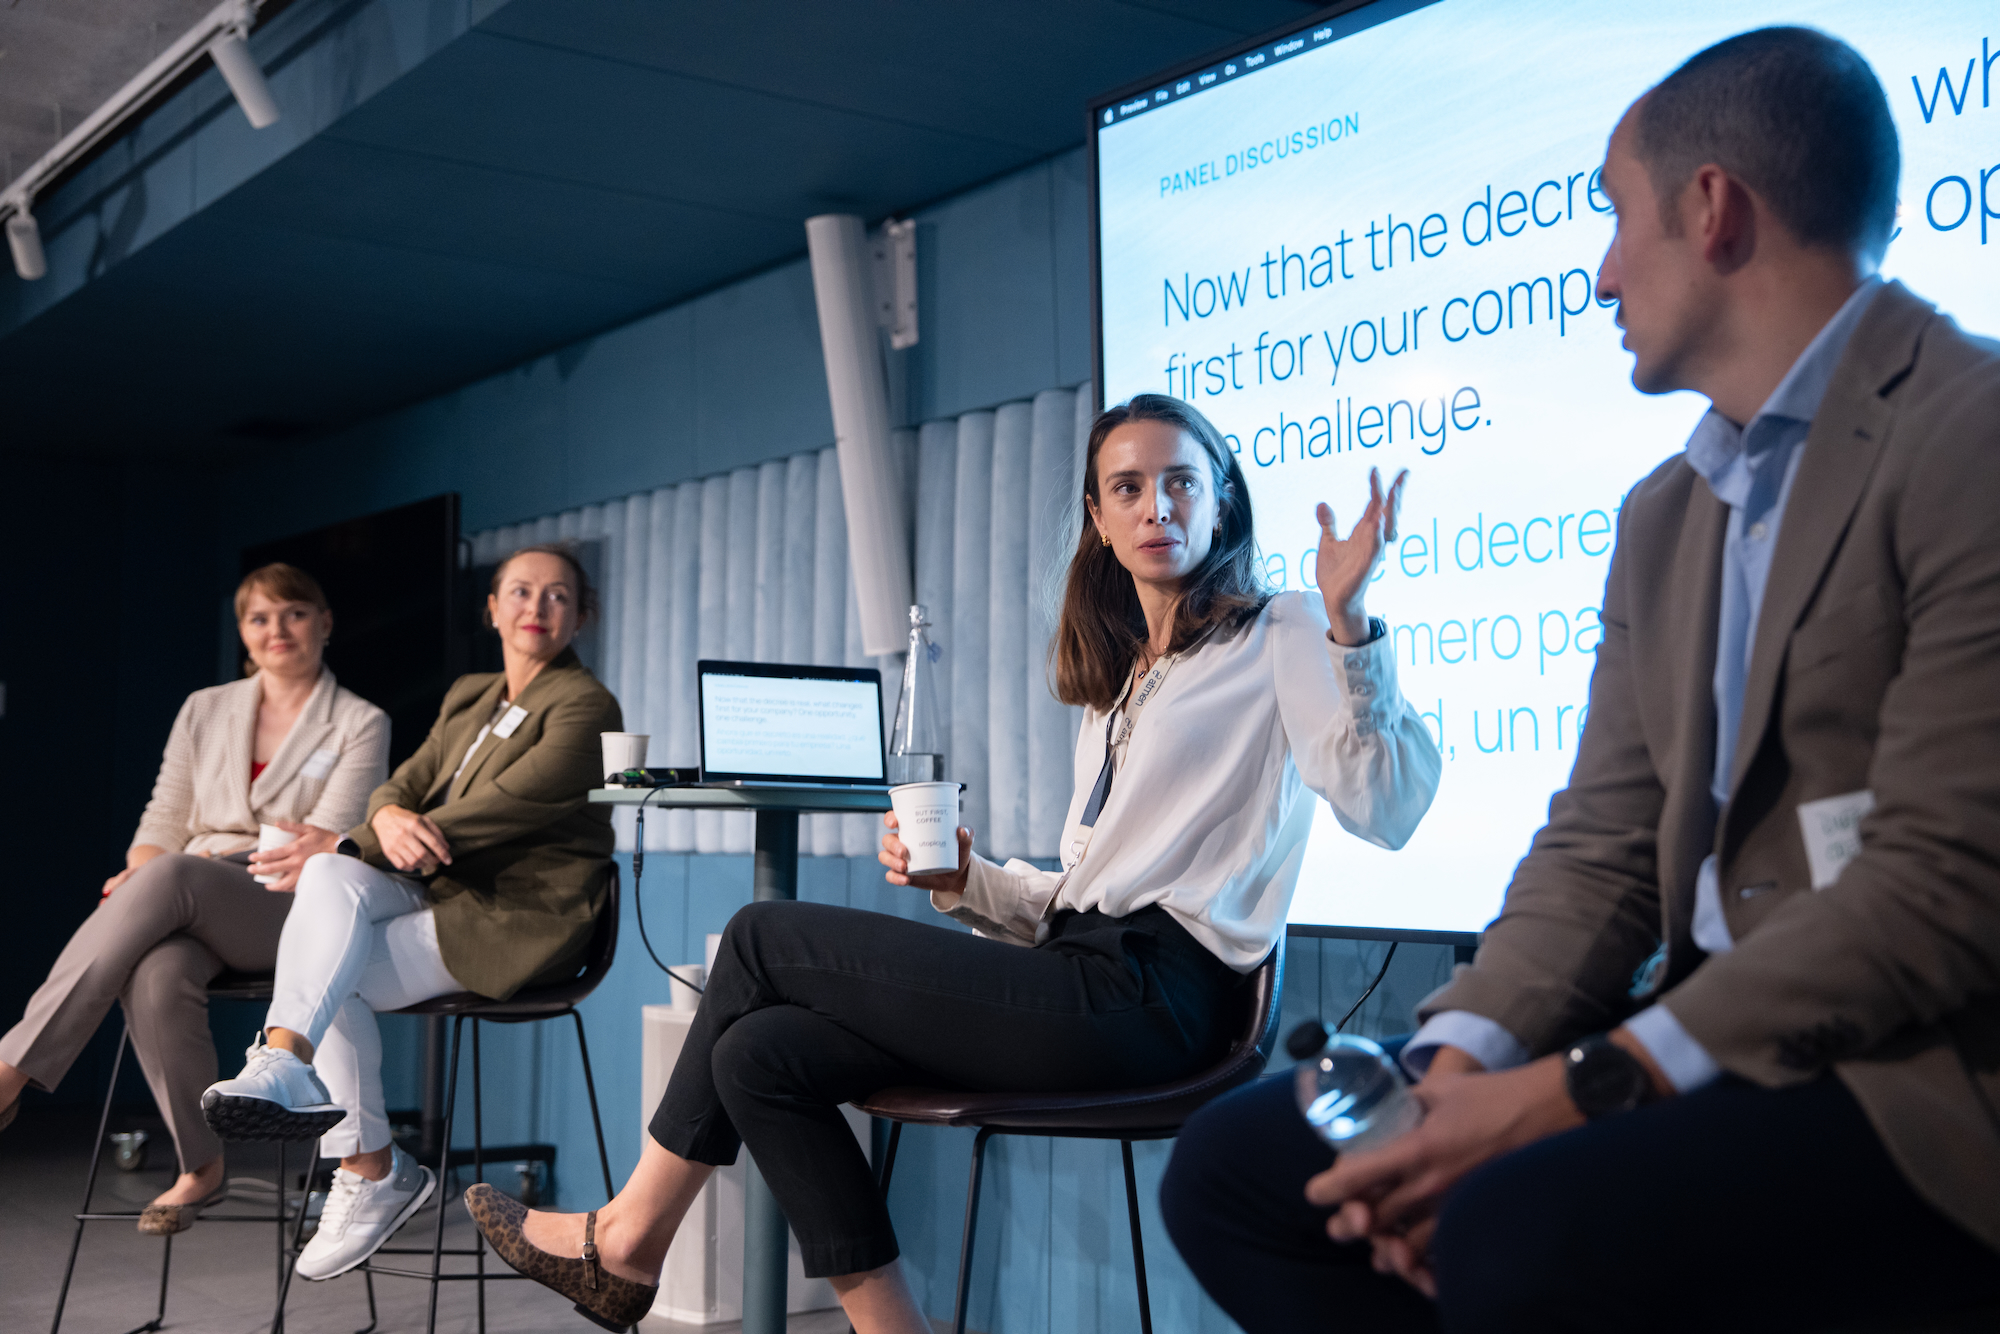
Beyond meeting regulatory requirements, certificates could also influence commercial decisions across the renewable fuels value chain.
The draft SICCRE framework outlines different certificate types and mechanisms for meeting obligations. It also proposes compensatory payments of €2,110 per tonne of oil equivalent for advanced biofuels and biogas, and €4,180 per tonne of oil equivalent for RFNBOs (approximately €12/kg of hydrogen). These figures provided a concrete reference point for discussing certificate economics.
But the conversation also turned to who can claim the value of those certificates.
Spain's new sujeto habilitado role allows eligible producers, including certain RFNBO producers, to obtain certificates even when they are not themselves subject to transport obligations.This opens up new possibilities, but also introduces decisions that businesses will need to consider carefully.
For example, when a producer sells through a trader, who is entitled to claim the certificate, and how does that affect the commercial value of the transaction?
It's a good illustration of how a regulatory provision can influence decisions beyond the teams responsible for regulatory requirements.
Certificates are only one part of the equation. The information supporting them also needs to move reliably between producers, traders, suppliers and the systems responsible for verifying regulatory requirements.
SICCRE is intended to cover the renewable fuels value chain and connect with the EU Union Database. For renewable gases, the discussion also explored how sustainability documentation, Guarantees of Origin and information about final consumption will interact.
The goal is a more connected system, but achieving it requires coordination between registries, reliable data and processes that can accommodate cross-border transactions.
For businesses managing multiple fuels or operating across different European markets, keeping that information consistent is crucial.
he discussion reinforced a central point: traceability must be maintained throughout the supply chain, rather than addressed only at the point of certification.
Beyond the technical details, much of the conversation came back to a commercial reality: renewable fuel projects need more than targets; they need a market they can plan around.
The shift towards GHG emissions reductions creates opportunities, particularly for fuels that can demonstrate strong emissions performance. Yet differences in national implementation, evolving EU requirements and questions around how different transport regulations interact still complicate long-term planning.
A leaked impact assessment related to RED IV added to that uncertainty, suggesting a possible shift from binding RFNBO targets to indicative ones. While not a formal legislative proposal, it raised concerns about investment confidence and the certainty needed to secure long-term offtake agreements.
Participants did not agree on every implication, but the importance of predictable demand signals was a recurring theme throughout the discussion.
After all, regulation can help create a market, but businesses still need the confidence to invest in it.
A big thank you to Moeve, HEYGAZ Biomethane and Enagás for co-hosting, to Diego Crespo, Carmen Rodríguez Valdés and María Deryugina for sharing their expertise, and to everyone who joined us and contributed to the conversation.
The conversations in Madrid have already sparked ideas for future topics and locations.
Stay tuned for the next edition!